October is the month when smart photographers stop thinking about this year's money like artists and start thinking about it like business owners. Every photographer tax deduction you are going to claim for 2026 has to be locked in by December 31. The gear you buy in January will not help you this year. The mileage you never logged is gone. The home studio you never measured stays unclaimed. The good news is that the system rewards the organized: a freelance photographer earning $75,000 typically writes off $15,000 to $22,000 in ordinary and necessary business expenses, which can cut the federal tax bill by roughly $4,000 to $6,000, according to Jupid's 2026 photographer tax guide. This post is the year-end checklist I would hand any photographer who asks me how the business side actually works, plus a video that explains the one tax form every photographer needs to understand: Schedule C.
A necessary disclaimer up front: I am a photographer, not a CPA. This is general information about photographer tax deductions, not tax advice. Tax rules change, and individual situations vary. Check everything here against the current IRS rules and talk to a qualified tax professional before you file.
Contents
- Watch: Schedule C explained for photographers
- The short answer: what counts as a photographer tax deduction
- The 2026 year-end checklist: 8 moves before December 31
- My take after 27 years of running a photography business
- FAQ: photographer tax questions, answered
- Book a session
The short answer: what counts as a photographer tax deduction
A photographer tax deduction is any ordinary and necessary cost of running your photography business, reported on Schedule C of your personal tax return. That includes camera bodies, lenses, and lighting expensed under Section 179, business mileage, a qualifying home studio, editing software and gallery platforms, business insurance, contract labor like second shooters, advertising, professional education, and half of your self-employment tax. Expenses that are personal, like everyday clothing or commuting, do not qualify even if they feel work-related.
Watch: Schedule C explained for photographers
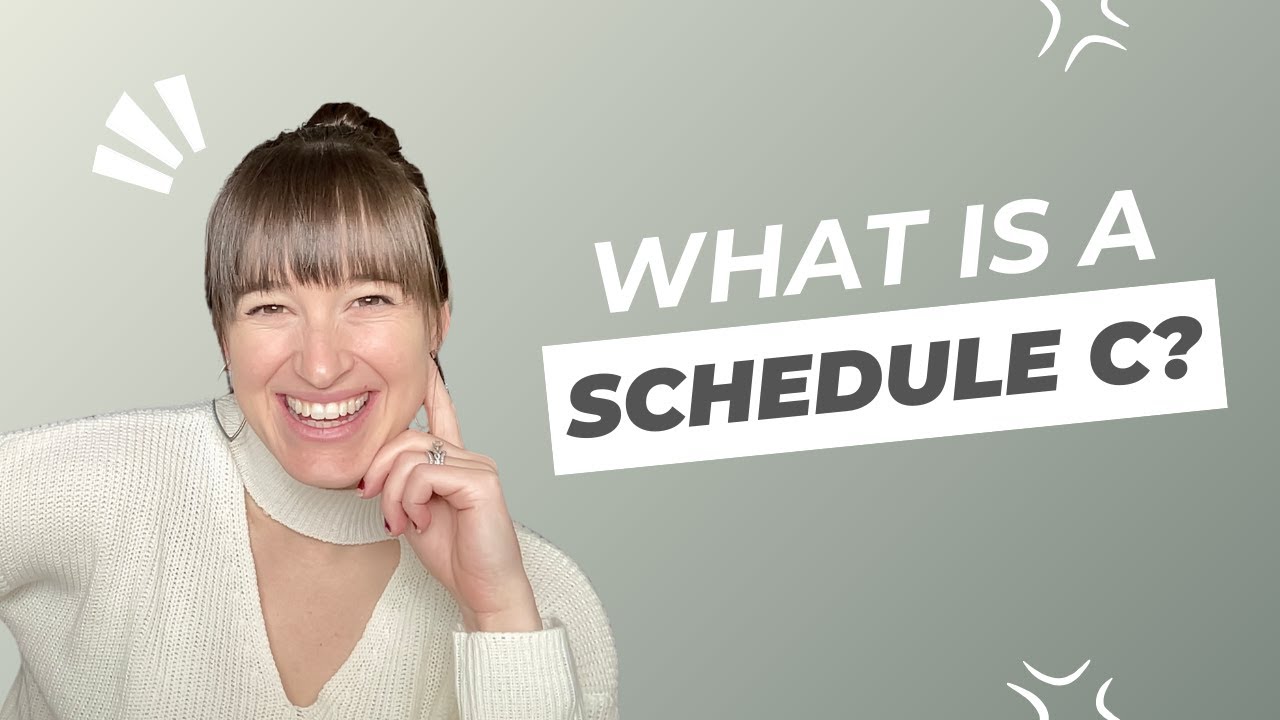
Photographer and tax educator Heather Marie breaks down Schedule C, the form where every photographer tax deduction lives. In her video "What Is a Schedule C, and How Do Photographers Use It?", she explains what Schedule C is and why it is essential whether you are a sole proprietor or a single-member LLC, walks through the form's two key sections, reporting your income and deducting your expenses, flags the biggest mistakes photographers make on it, and lays out simple steps to make tax season easier. She also runs a free masterclass, "Maximizing Your Tax Deductions as a Photographer," covering five commonly missed deductions. She says she cut her own taxable income by $12,817 last year using them, which tells you how much money disorganization costs the average photographer.
The 2026 year-end checklist: 8 moves before December 31
Every item below has a hard deadline or a number that changes for 2026. Work through them in order. Each one is sourced from the current-year guides linked at the end of this post.
1. Expense your gear under Section 179 before December 31
Section 179 is the single biggest lever a photographer has. It lets you deduct the full purchase price of cameras, lenses, lighting, computers, and other qualifying equipment in the year you place it in service, instead of depreciating it over five years. For 2026 the Section 179 limit is $2,560,000, so in practice your entire gear budget is deductible in year one. Three catches, straight from the Jupid 2026 guide: the gear must be used more than 50 percent for business to qualify, Section 179 cannot exceed your business taxable income for the year (the excess carries forward), and if business use later drops to 50 percent or below you have to recapture the excess deduction as income. The election goes on Form 4562. The year-end play is simple: if you already planned to buy a body, a lens, or a computer for 2027, buying it before December 31 pulls the whole deduction into this year's return. One alternative worth knowing: 100 percent bonus depreciation is permanently available for qualifying property placed in service after January 19, 2025, and unlike Section 179 it can create a loss. For smaller items, the de minimis safe harbor lets you expense anything costing $2,500 or less per item outright, memory cards, hard drives, and modifiers included.
2. Finish your mileage log (and use the right 2026 rate)
Driving to shoots, scouting locations, picking up rentals, and meeting clients all generate deductible mileage, reported on Schedule C line 9. For 2026 the standard rate is split: 72.5 cents per mile for miles driven January 1 through June 30, and 76 cents per mile from July 1 onward. The part photographers botch is documentation. A mileage log reconstructed from memory at tax time is exactly what auditors reject. Log each drive as it happens with the date, destination, business purpose, and miles, then apply the rate that was in effect when the miles were driven. One underused fact from the LegalClarity guide: if your qualifying home office is your principal place of business, drives from home to a shoot count as deductible business mileage. Without a home office, the drive to your first appointment of the day is nondeductible commuting. The home office section below is worth more than it looks.
3. Measure your home studio and claim it
If you edit, cull, invoice, and run client communication from a dedicated space in your home, the home office deduction is likely the most underclaimed write-off in photography. The IRS imposes two tests: the space must be used regularly and exclusively for business, and it must be your principal place of business or a place where you meet clients. A spare room set up as an editing suite qualifies. The corner of a bedroom you also sleep in does not. You calculate it two ways. The simplified method is $5 per square foot up to 300 square feet, a $1,500 maximum, with no receipt tracking. The actual expense method takes your business-use percentage of the home's square footage and applies it to rent or mortgage interest, utilities, insurance, and repairs, which often produces a much larger number, especially for renters. It is reported on Form 8829 and flows to Schedule C line 30. Measure the room before year end so the number is ready when your CPA asks.
4. Reconcile software, subscriptions, and gallery platforms
The modern photographer's software stack is a quiet five-figure expense over a career and it is 100 percent deductible in the year you pay for it. Adobe Creative Cloud, Capture One, gallery delivery (Pixieset, ShootProof, Pic-Time), studio management (HoneyBook, Dubsado), cloud storage, and backup services all go on Schedule C line 27a as other expenses. Jupid's 2026 example stack, Creative Cloud, a gallery platform, studio management, cloud storage, and backup, totals about $1,640 a year. Before December 31, pull one statement from each and confirm every subscription is actually business. Kill the ones you do not use, and prepay the ones you do if the annual plan is cheaper, the deduction lands in 2026 either way.
5. Tally contract labor and issue 1099-NECs
Every second shooter, assistant, retoucher, and editor you paid this year is a deductible business expense on Schedule C line 11. The compliance step photographers forget is the paperwork going the other direction: for each contractor you paid $600 or more, you generally need to issue a Form 1099-NEC, and the deadline to furnish it is early in the new year. January-you will thank December-you for collecting W-9s now, while everyone still remembers the gig. Keep invoices for every contractor payment regardless of amount. If the IRS ever asks, the paper trail is the deduction.
6. Make the January 15 estimated payment
No employer withholds taxes from photography income, so the IRS expects you to pay as you go. If you expect to owe $1,000 or more in federal tax for the year after withholding and credits, quarterly estimated payments are required, made with Form 1040-ES. For the 2026 tax year the four deadlines are April 15, 2026, June 15, 2026, September 15, 2026, and January 15, 2027, which covers your September through December income. Missing them triggers an underpayment penalty calculated as interest on the shortfall. The safe harbor most photographers should know: pay at least 100 percent of last year's total tax liability across the four quarters, 110 percent if your adjusted gross income exceeded $150,000, and the penalty does not apply even if you end up owing more at filing. December is when you true up the final quarter.
7. Capture the 20 percent qualified business income deduction
On top of every write-off above, most freelance photographers qualify for the Section 199A qualified business income deduction, which removes up to 20 percent of net business income from taxable income. It is not an expense, it is a flat percentage reduction you claim on Form 1040 whether or not you itemize, and it does not reduce self-employment tax, only income tax. For 2026 the full 20 percent is available without limitation when total taxable income is below $201,750 single or $403,500 married filing jointly. Photography is generally not classified as a specified service trade or business, so the deduction survives at higher incomes where fields like law and consulting lose it. On $80,000 of net profit, that is up to $16,000 removed from taxable income for doing nothing but operating as a sole proprietor or single-member LLC.
8. Know what you cannot deduct
This is the section that saves you from an audit adjustment. Everyday clothing is not deductible, even if you bought it specifically for shoots or client meetings, because it is suitable for daily wear. Wardrobe your subjects wear is a different category. Commuting is not deductible. The personal-use share of any mixed-use asset is not deductible, only the business percentage. The value of your own unpaid time, editing until 2 a.m., shooting for exposure, is never a deduction. Entertainment is not deductible at all, and business meals are capped at 50 percent. And if your photography is not run for profit, post-2017 rules disallow deducting expenses against other income, so keep separate books, a separate bank account, and a clear profit motive. When in doubt, the IRS test is two words: ordinary and necessary.
My take after 27 years of running a photography business
Nobody hands you a finance degree when you pick up a camera. I learned the business side the way most photographers do, by getting it wrong early and paying for the lesson. There is a chapter in my book called Take Control of Your Life, and the line that has stayed with me all these years is this: when you are running your own business, you need to take control of your life, whether or not people support you, you need to achieve your goals and do what you love. Taxes are the least glamorous part of that sentence, but they are part of it.
Early in my career I was selling pictures to magazine editors, shooting red carpets like the Teen Choice Awards, making real money for the first time and meeting the managers and agents who ran Hollywood. Back then the magazine business was thriving and the checks were big. What I understand now, that I did not understand then, is that the money you keep is a skill, separate from the money you make. A great shoot with no bookkeeping behind it is just an expensive hobby with good lighting.
Here is what discipline looks like in practice, after 27 years. I keep a separate business bank account and every client payment runs through it. Every business drive gets logged. Every receipt for gear, software, travel, and insurance goes into one system, not a shoebox, not a camera bag pocket. And I pay professionals for the parts I should not do myself: my bookkeeper and my CPA are deductible on Schedule C line 17, and they have saved me multiples of their fees. The photographer who treats the business like a business is the one still standing in year ten, year twenty. The craft gets you hired. The books keep you in business. If you take one thing from this checklist, take this: do the boring paperwork in December, and April becomes a non-event.
If the money side of photography is new to you, two posts on this blog pair naturally with this one. My guide to photography licensing covers how usage rights and buyouts decide what your work is actually worth, which is the income half of this equation. And my playbook for raising your rates for 2027 walks through setting prices that survive taxes, insurance, and slow months, because a rate that does not account for the 15.3 percent self-employment tax is not a real rate.
FAQ: photographer tax questions, answered
Can photographers write off camera equipment?
Yes. Section 179 lets you deduct the full purchase price of cameras, lenses, lighting, and editing computers in the year you start using them for business, up to $2,560,000 in 2026. The equipment must be used more than 50 percent for business, and you elect it on Form 4562. Bonus depreciation offers a second route to a first-year write-off, and items costing $2,500 or less each can be expensed outright under the de minimis safe harbor.
Can I deduct the clothes I wear on photo shoots?
No, not if the clothing is suitable for everyday wear. The IRS disallows outfits you wear to client meetings or shoots when you could also wear them in daily life, even if you bought them specifically for work. Clothing and wardrobe worn by your subjects as props or costumes is a different category and is deductible.
Do photographers have to pay quarterly estimated taxes?
If you expect to owe $1,000 or more in federal tax for the year, yes. The IRS requires quarterly estimated payments on Form 1040-ES, with 2026 deadlines of April 15, June 15, September 15, and January 15, 2027. Paying 100 percent of last year's total tax across the four quarters, 110 percent if your adjusted gross income exceeded $150,000, satisfies the safe harbor against underpayment penalties.
Is a home studio tax deductible?
Yes, if the space is used regularly and exclusively for your photography business. The simplified method gives you $5 per square foot up to 300 square feet, a $1,500 maximum, with no expense tracking. The actual expense method applies your business-use percentage to rent or mortgage interest, utilities, insurance, and repairs, and often yields a larger deduction. Report it on Form 8829.
What is Schedule C and do photographers need to file one?
Schedule C is the tax form where sole proprietors and single-member LLCs report business income and expenses. Every photographer tax deduction on this checklist flows through it: gross income on line 1, expenses on their respective lines, and net profit on line 31, which then feeds Schedule SE for the 15.3 percent self-employment tax. Heather Marie's video above walks through the whole form.
Book a session
Year end is also booking season. Holiday portraits, updated headshots for the new year, and brand sessions for 2027 launches all get scheduled in October and November, and my calendar fills fast. If you want portraits with the kind of lighting and direction that only comes from 27 years behind the camera, get in touch here and tell me what you are planning. And if you are a photographer building your own business, these nine client-getting strategies are the revenue side of everything this post covers. Revenue first, deductions second, profit always.
Which of these eight moves will you handle before December 31? Tell me in the comments, I read every one.